Many people think that investing in financial instruments will change their life in quick succession. The truth is that every successful investor has this thing called an investment portfolio, this portfolio contains a mix of financial instruments that are going to grow and protect your funds.
How every financial instrument fit and work together is more important than choosing one itself, also index funds can be included in the investment portfolio alongside other instruments.
In this guide you will find what a successful portfolio is and how you are going to allocate your money in the financial market.
What is an investment portfolio?
An investment portfolio is some kind of report that contains information on every financial asset an investor owns. This is not a product but rather a set of reports. You can’t buy a portfolio, you make one by purchasing various financial instruments, and that collection is your portfolio.
This will help investors grow their wealth by choosing the right variation of investment which is also called asset allocation that balances the risk and supports the investor's financial goals. This is why a diversified portfolio can mitigate your losses from one investment.
How Does an Investment Portfolio Work?
An investment portfolio compiles a number of financial assets with the aim of a specific financial goals and managing risk. The financial assets have their own share from the overall funds.
1. Asset allocation and weights
Asset allocation is a distribution process of each type of investment, this process should be based on the investor's own goals, risk, and timeline. Each of the asset classes is in percentage, take this Gotrade simulation for example:
Nothing in the simulation was bought or sold, the portfolio changed shape on its own, which needs a rebalancing.
Expected portfolio return is quite simple; the weighted average of the expected return of each asset multiply by weight of each of the assets, then add the results.
Expected Return of the Portfolio E(Rp) = Σ (Weight of each asset × Expected Return of each asset)
This formula is not a forecast, a target, or something that owes you, the output changes as you change the numbers.
What Are the Main Types of Investment Portfolio?
Portfolios can be described in two ways: based on the assets they hold and based on the purpose of their creation. The tables below describe each of these perspectives.
Asset class types
Asset class | What it is | Typical role in a portfolio | Main risk |
Equities | Shares in companies | Growth | Large price swings, loss of capital |
Bonds | Loans to governments or companies | Income, ballast | Rate and credit risk |
Cash | Deposits and money market holdings | Liquidity | Inflation erosion |
REITs | Listed property vehicles | Income, property exposure | Rate sensitivity, sector concentration |
ETFs and index funds | Pooled exposure to many holdings | Broad access in one purchase | Inherits the risk of whatever it tracks |
Portfolio types
Portfolio type | What it emphasises | Trade-off |
Growth | Capital appreciation, weighted toward equities | Larger swings, longer horizon needed |
Income | Regular cash from dividends and interest | Less exposure to long-run capital growth |
Balanced | A mix of growth and income assets | Trails both in the conditions that favour either |
Defensive | Capital preservation, weighted toward bonds and cash | Inflation is the binding risk over time |
Investment Portfolio Limitations
An Investment portfolio has limitations because the mix of what you hold has historically driven the result more than the individual choices inside each bucket.
Based on The Global Investment Returns Yearbook Journal which covers 5 markets, ranging from 1900 to 2024. They found annualised returns of 5.2 percent for worldwide equities, against 1.7 percent for bonds and 0.5 percent for bills.
Those gap are even wider on short period as S&P Dow Jones Indices data shows that as per 4 September 2026. The S&P GSCI commodity index increased 52.15 percent for the year while The S&P U.S. Aggregate Bond index sat at minus 0.05 percent. No one knows 52 percentage points gap inside eight months, this is why holding more than one asset class is the right move to avoid that uncertainty.
2. Optimal asset sizing
Research in the Journal of Finance in 1968 measured how portfolio distribution decreased as randomly selected stocks were added and the rate of decline slowed rapidly and found that the majority of diversification benefits can be achieved by holding between 10 and 15 assets in a portfolio. But a later research in 1987 by Meir Statman questioned this figure and argued that a more appropriate number is closer to 30 assets.
3. Diversification limitations
Asset diversification only reduces the risk inherent in any single investment asset and does not eliminate overall market risk, as the risk still remains even after company-specific risk has been removed.
Even a 400 stocks portfolio will still decline in value whenever the market falls, spreading the investment this way only changes the type of the risk, not eliminate it
What Are the Risks and Things to Watch?
Here are the risk of the managed portfolio before you build one yourself.
1. Diversification does not prevent losses
A diversified portfolio can’t be a guarantee, it can also fall when the overall market declines, the risk between assets increases during severe market stress so the protection of the portfolio weakens when it is needed the most because holdings that normally move independently in value start moving together.
2. Concentration hides inside broad holdings
Most of the US index funds are weighted by company size which recently accounted for roughly 35 to 40 percent of the S&P 500. If you hold three index funds with the same weightings approach then you may hold the same companies three times. Checking the top holdings list for each index fund is the only way to see the extent of the ownership overlap.
3. Drift and the cost of rebalancing
A passively moved portfolio will have a drift, as the 60/30/10 split will drift to 64.3/26.8/8.9 and will need a rebalancing to restore the original split. This rebalancing requires costs and taxes and the more you rebalance it the more it costs and the less you rebalance it the more your portfolio will drift.
How to Build an Investment Portfolio With Gotrade
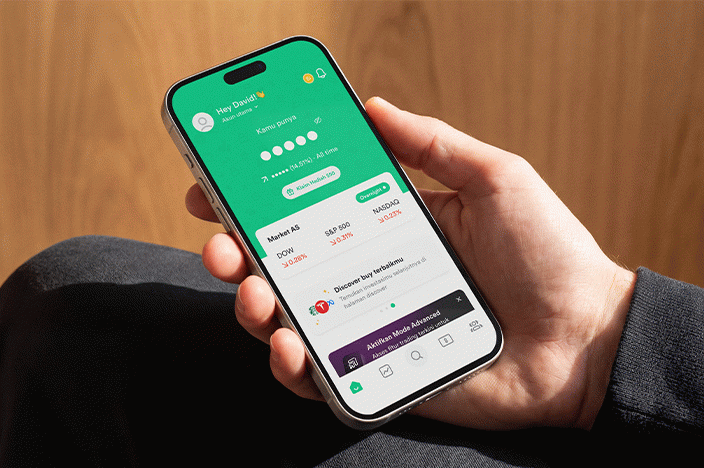
Start building your investment portfolio with Gotrade, that gives you access to US stocks and ETFs through fractional shares. You can start small and buy a portion of a share from $1 rather than paying the whole stock
Here are the steps to start first investment with Gotrade:
Open an account and complete identity verification.
Decide how many separate holdings you want to start with.
Search for each one by ticker symbol.
Enter a dollar amount for each, which is what sets the weights.
Review the holdings together rather than one at a time.
A $50 starter portfolio, with real numbers
Say you have $50 and want one growth stock, one broad-market fund, and one bond fund. You could put $20 into Apple (AAPL), $20 into the Vanguard S&P 500 ETF (VOO), and $10 into the Vanguard Total Bond Market ETF (BND). That is a 40/40/20 split across a single company, a diversified equity fund, and a fixed income fund, the same three asset classes from the table above.
Gotrade's trading fee runs 0.15% to 0.3% per transaction, with a $0.10 minimum per trade. On a $20 fractional order, that minimum is what actually applies, so each of the three buys above costs $0.10 regardless of the exact percentage, about $0.30 total to open the position. That minimum matters more when you split a small amount across several holdings at once than when you buy one position outright, so it's worth factoring into how many tickers you open on day one.
Fractional ownership carries one more real limit worth knowing before you start. If AAPL later pays a dividend, your fractional position still qualifies, but if the payout works out to less than $0.01 on your slice, you won't receive anything since no broker can pay a fraction of a cent.
Conclusion
Building an investment portfolio comes down to a handful of decisions repeated with discipline: which asset classes to hold, how much weight to give each one, and how often to bring that mix back to its original shape. None of these steps guarantees a specific outcome, but skipping them leaves your results to chance rather than to a plan you actually chose.
Where you start matters less than that you start with intention, Gotrade lets you research holdings, buy fractional shares from $1. Open a Gotrade account to see how your holdings and their dividend payments come together in one place.
This content is for educational purposes only and is not investment advice or a recommendation. Investing carries risk, including the possible loss of principal. Diversification does not guarantee a profit or protect against loss.